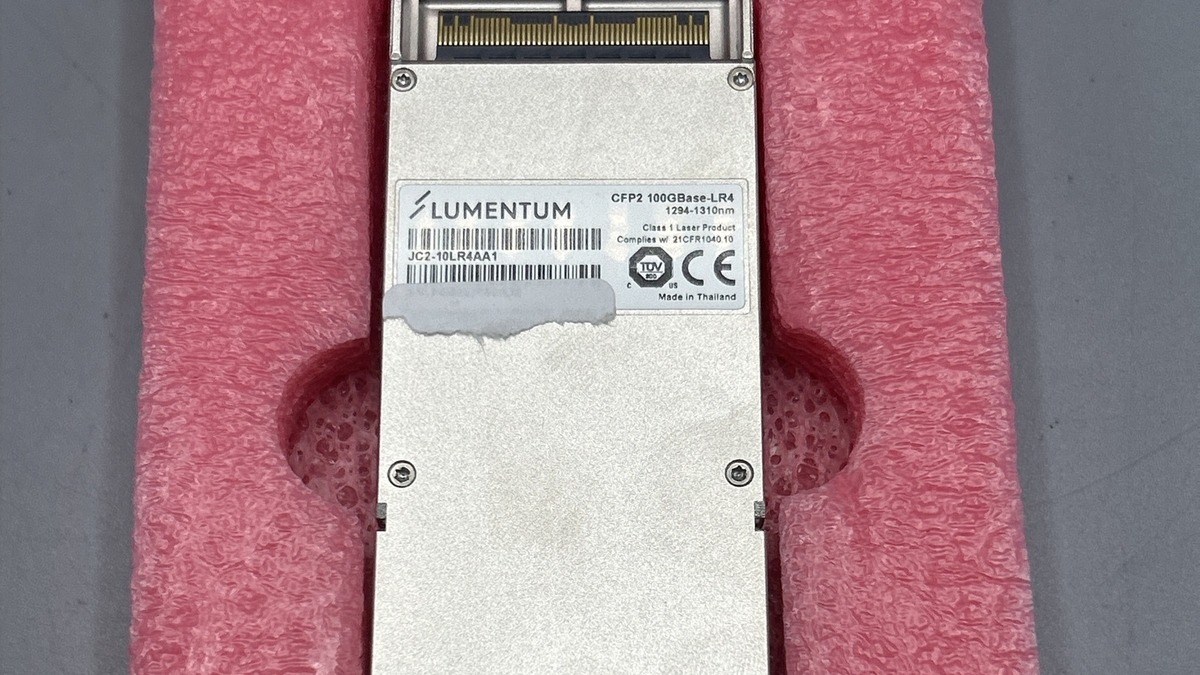
Marvell wants to buy the laser to its own chip — and its shareholders are treating the plan like an accident.
Marvell Technology is in advanced talks to acquire Lumentum, the optical-components maker whose lasers, photonic circuits, and high-speed transceivers move data between GPUs inside AI data centers, Bloomberg reported Wednesday. The deal would be all stock and could be announced as early as next week. At Lumentum's roughly $85 billion market value against Marvell's $194 billion, it would be "one of the biggest deals in tech," as Stifel analyst Tore Svanberg told MarketWatch.
The business logic reads obvious in hindsight. Lumentum makes the lasers; Marvell makes the digital signal processors that sit next to them inside optical transceivers. BNP Paribas estimates the two companies' components together account for about 75% of the bill of materials in a typical PAM4 optical transceiver, according to coverage of the bank's note. As AI clusters shift from copper to optical GPU-to-GPU links, owning both sides means owning the subsystem — a play Broadcom already runs, pairing its switching silicon with an in-house laser portfolio. BNP Paribas projects the data-center optical-transceiver market growing from roughly $35 billion in 2026 to $91 billion by 2030, and says a completed deal could lift Marvell to about $28 billion of calendar-2027 revenue. "This convergence of semiconductor and optical technology is very critical for AI networking," Svanberg told MarketWatch.
Then the money. Marvell has about $3.9 billion in cash — under 5% of Lumentum's market cap — so any deal has to be paid in Marvell stock, Wolfe's Chris Caso pointed out. Seaport's Jay Goldberg says the market assumes Marvell will also pay a large premium, and that's reason alone to punish the shares. It did: Marvell fell 12% on Thursday while Lumentum rose 2%, the textbook split for a leaked all-stock deal where the buyer looks expensive. Investors are "freaking out," Svanberg said, over the deal's size and the fact that any merger would need both U.S. and Chinese regulatory approvals — and the Chinese process can be lengthy.
There's a third party in the room. Nvidia is both a Lumentum customer and a $2 billion shareholder since March, per AI Weekly, meaning it would watch one of its optical suppliers get absorbed by a custom-silicon rival. And Evercore ISI's Amit Daryanani says his clients keep asking a sharper question: why would Lumentum sell at all, when it's told investors the business is sold out through fiscal 2029? Morningstar puts the odds of a deal below 50% and worries Marvell overpays.
What to watch: the premium, the share count, and whether Nvidia — or someone else — decides it would rather own Lumentum's lasers itself. The AI boom keeps consolidating its plumbing, and the plumbing is starting to cost like the house.
— via MarketWatch